Repossessions are considered a major derogatory event in terms of credit scoring. They can hurt your credit score and make it difficult to qualify for new financing in the future. Yet not all repossessions that show up on credit reports are valid.
And even repossessions that did occur may contain credit reporting errors that could damage your credit scores unfairly. If you believe a repossession on your credit report contains inaccurate information, here are some tips that may help you.
What is a Repossession?
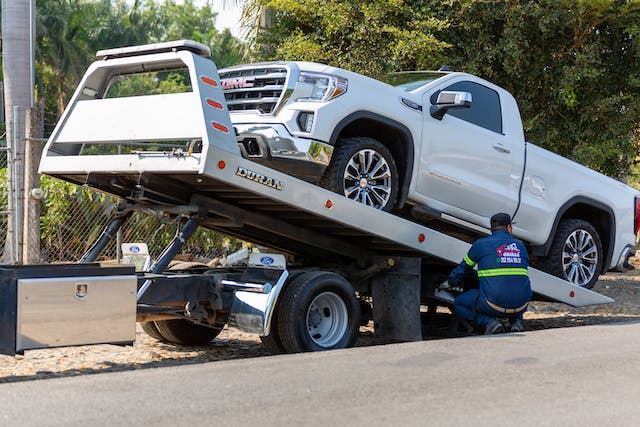
When you fall behind on your auto loan payments, the lender may take back your vehicle to try to recuperate its loss. This process is known as a repossession.
There are two primary types of repossessions:
- Voluntary repossession or voluntary surrender, happens when you proactively turn over the vehicle you financed to the lender.
- Involuntary repossession occurs when a repossession company comes out to seize your vehicle on the lender’s behalf.
From a credit standpoint, there’s little difference between a voluntary and an involuntary repossession. Either type of repo could potentially have a severe impact on your credit score.
However, with some lenders, a voluntary repossession might work in your favor. When (and if) you want to borrow money from the same lender again in the future, it might be more willing to take another chance on you if you willingly cooperated prior to your repossession.
If you can qualify for a new loan from the same lender, and there’s no guarantee of that, expect the rate and terms to be less favorable due to your higher credit risk.
What Does the Repossession Process Look Like?
When you default on an auto loan, your lender may be able to take the vehicle back without warning depending on where you live. In some states, one missed payment may be enough to put you in jeopardy of losing your car.
Every state has different laws, but here are the basic steps of the repossession process.
- You default on your loan, according to the terms of the contract.
- The creditor takes possession of your car, through voluntary or involuntary means.
- The creditor typically reports the repossession to the credit bureaus the next time it sends in monthly account updates.
- The credit bureaus add a notation to your credit reports such as “repossession,” “voluntary repossession,” or “involuntary repossession.”
- Your vehicle is sold, often at auction. Depending on your state of residence, you may have the opportunity to redeem your vehicle before this point (aka, pay the creditor what you owe, including repossession fees.)
- The lender applies the proceeds from the sale, minus fees, to your outstanding balance.
- Any deficiency balance, meaning the loan amount the sale didn’t cover, may remain on your credit report.
- The creditor may opt to sue you for the deficiency balance, as long as your state’s statute of limitations hasn’t run out.
How Long Do Repossessions Stay on My Credit Report?
The Fair Credit Reporting Act (FCRA) sets limits on how long most negative information can stay on your credit report. A repossession can stay on your report for about seven years from the original delinquency date, meaning the date you first fell behind on the payments that led to it.
How do Repossessions Affect My Credit Score?
Credit scoring models treat repossessions as a major derogatory event. But it’s nearly impossible to predict exactly how much a repossession might affect your credit score.
Everyone’s credit report is different. The credit score impact that a repossession has on a credit report with severe damage is going to be different than its impact on an otherwise clean report.
In the first example (the damaged credit report), adding a repossession will likely have some adverse credit scoring consequences. Yet in the second example (the otherwise clean credit report), a notation of repossession could have a severe credit score impact.
Either way, adding a repossession onto a credit report will hurt, not help you. It can lower your credit score, perhaps by a lot, and make it hard to qualify for new accounts.
According to Experian, an involuntary repossession might hurt your credit score a little more than a voluntary one. Yet both types of repossessions can be extremely negative from a credit scoring standpoint.
Can I Get a Loan After a Repossession?
Qualifying for a new loan or credit card after a repossession can be difficult, but not impossible. If you find a lender that’s willing to do business with you, you should expect to pay higher interest rates and fees when you borrow money. You might also qualify for lower loan amounts and credit limits.
If you want to rebuild positive credit after a repossession, certain types of accounts do offer easier qualification criteria. Certain secured credit cards and credit builder loans, for example, might be a good fit in this situation.
Can Repossessions be Removed from a Credit Report?
A repossession that’s reported accurately can legally stay on your report for the full reporting period. You still have two options. You can dispute a repossession that has errors, or you can ask the creditor to stop reporting it early, which the creditor may decline.
1. Disputing a Repossession
The FCRA lets you dispute any item on your credit report that you believe is incorrect. So, if a repossession on your credit report features a wrong balance, invalid dates, or other questionable information, you can dispute it and ask the credit bureau to investigate.
A credit bureau generally has 30 days to investigate a dispute. If the information turns out to be inaccurate or can’t be verified, the bureau must correct it or delete it from your report.
You have the right to handle disputes on your own, for free. If that’s more work than you have time for, a reputable credit repair company can handle the disputes for you. To see where you stand, start a free credit review.
2. Negotiating for Early Removal
Credit reporting is voluntary. Creditors report repossessions and other account information to the credit bureaus because it helps them collect debts. But a creditor can choose not to report an account (or ask a credit bureau to remove an account) if it chooses to do so.
A creditor doesn’t have to remove an accurate repossession, and it may say no. Accurate information can legally stay for the full reporting period. Still, you can ask.
If you have the money to bring your loan current (or settle the deficiency balance on an already repossessed vehicle), you can ask a creditor or collection agency if it’s willing to accept payment in exchange for deletion.
In rare cases, a creditor or debt collector might be willing to negotiate the early removal of a repossession from your report. If you’ve experienced a hardship, like a job loss or illness, you can share these extenuating circumstances with your creditor.
There’s no guarantee this approach will work, but you might find someone who is willing to help you. Above all, if a creditor or collection agency agrees to delete a repossession from your credit report, get the offer in writing.
Should I Pay Off a Repossession?
Paying off a repossession may or may not improve your credit score. The score impact (or lack thereof) largely depends on which credit scoring model a lender uses.
Some newer credit scoring models ignore collection accounts with zero balances. Older scoring models (like the older FICO versions many mortgage lenders still use) treat a $0 balance collection roughly the same as a collection with a balance. With older scoring models, paying or settling a collection often does little to nothing for your score.
Yet, credit score impact aside, you may still want to pay off your deficiency balance if you can afford to do so. If you don’t pay off a repossession, there could be unpleasant consequences.
What Happens if I Don’t Pay a Repossession?
Having a repossession with an outstanding balance may cause several potential problems.
- The lender or collection agency might sue you. If you lose the lawsuit, whether you had no solid defense or didn’t show up, the judge will enter a judgment against you. In some cases, a judgment could open the door to the lender taking further action against you, like a wage garnishment.
- A judgment can make it hard to qualify for new loans. Judgments no longer appear on credit reports thanks to the National Consumer Assistance Plan (NCAP). Yet they may still cause problems when you apply for certain types of loans. Mortgage applications, for example, commonly include a public records search which may reveal judgments filed against you. Some lenders require all judgments to be paid before you can qualify for new financing.


How Can I Dispute a Repossession on My Credit Report?
You can dispute a repossession by sending a letter to the credit bureau that’s reporting wrong information on your credit report: Equifax, TransUnion or Experian. The credit bureau generally has 30 days to investigate your claim, and up to 45 days in some cases, such as when you send more information after the dispute begins.
In addition to mailing your dispute to the credit bureaus, you can also submit disputes online or over the phone.
Whichever way you send it, keep copies of your dispute and any documents you include. If you’d rather have help, a reputable credit repair company can handle the disputes for you, and you can start a free credit review.
Bottom Line on Repossessions and Your Credit
A repossession is a major negative mark that can stay on your credit report for about seven years. If yours shows a wrong balance, wrong dates or other errors, you can dispute it with the bureau reporting it. If you owe a deficiency balance, paying it when you can may help you avoid a lawsuit.

Ashley Davison
EditorAshley is currently the Chief Compliance Officer for Credit Saint, previously the Chief Operating Officer. Ashley got into the Financial world by working as a Logistics Coordinator at Ernst & Young. Coming from a previous career in education, she is eager to teach the world everything she knows and learn everything that she doesn’t! Ashley is a FICO® certified professional, a Board Certified Credit Consultant, a Certified Credit Score Consultant with the Credit Consultants Association of America, UDAAP certified, and holds a Fair Credit Reporting Act (FCRA) Compliance Certificate.